The latest AICPA REG test braindump guarantee a high score
TestBraindump provide you with REG braindump latest and REG test questions, which are created by our extraordinary teammates who study the REG braindump actual test for a long time. And we always check the update of the REG test braindump, the system will send you the latest version of AICPA REG real braindump once there is latest version released. So you can trust us about the profession and accuracy of our REG test braindump. If you still doubt our ability, you can download the free trial of REG braindump CPA Regulation study materials before you buy. If you decide to join us, you just need to send one or two days to practice REG test questions and remember the key knowledge of the test. I think if you practice our REG test braindump skillfully, you will pass the test easily.

Different versions according to your study habits
The version of Pdf is suitable to most common people because it can be print out and is easy to read. And you can share with other people about REG test braindump anytime.
The version of test engine is a simulation of the REG braindump actual test, you can feel the atmosphere of AICPA REG test exam and get used to the condition of the real test in advance. It only can support the Windows operating system. In the course of REG test exam, you will know your shortcoming and strength well.
The version of online test engine just same like test engine. But it can download REG test braindump study materials in any electronic equipment, such as: Windows/Mac/Android/iOS operating systems. The online version is only service you can enjoy from our TestBraindump. The most advantage of online version is that you can practice REG test questions anytime and anywhere even if you are unable to access to the internet. So you can do REG real braindump in the bus or waiting someone. You can learn anywhere.
The service of TestBraindump
Update Our Company checks the update every day. If you've bought REG test braindump from us, once there is the latest REG - CPA Regulation exam version, our system will send it to your e-mail automatically and immediately. And you can free update the AICPA REG braindump study materials one-year if you purchase.
Refund We promise to you full refund if you failed the exam with REG test braindump. Within 7 days after exam transcripts come out, then scanning the transcripts, add it to the emails as attachments and sent to us. After confirmation, we will refund immediately.
Discount We will offer you different discount for you if you became a member of us.
Payment Our payment is by Credit Card. But it can be bound with the credit card, so the credit card is also available.
After purchase, Instant Download: Upon successful payment, Our systems will automatically send the product you have purchased to your mailbox by email. (If not received within 12 hours, please contact us. Note: don't forget to check your spam.)
How can you stand out from thousands of candidates? How can you make your employer think highly of you? How can you qualify for the promotion? Passing REG test exam will make these dreams come true. As an important test of AICPA, REG test exam become popular among people. The considerable salary and decent work and different kind benefits, the chance of training, all these stuff attract to you. Passing REG braindump actual test is a new start for you. But it is a tough task. You have to sacrifice your rest time to practice the REG test questions and learn REG braindump study materials. And the worst result is that you maybe fail the exam, it will be a great loss of time and money for you. In case this terrible thing happens, TestBraindump will be your best partner to help you pass REG test exam.
AICPA REG Exam Syllabus Topics:
| Section | Weight | Objectives |
|---|---|---|
| Business Law | 10-20% | - Agency relationships - Secured transactions (UCC Article 9) - Contracts and UCC Article 2 - Debtor-creditor relationships and bankruptcy - Business structure legal framework |
| Ethics, Professional Responsibilities, and Federal Tax Procedures | 10-20% | - IRS audit, appeals, and collection procedures - Licensing and disciplinary systems - Tax preparer penalties and due diligence - Treasury Department Circular 230 rules - Ethics and responsibilities in tax practice |
| Federal Taxation of Property Transactions | 12-22% | - Capital vs ordinary asset classification - Recognition of gains and losses - Cost recovery, depreciation, and amortization - Like-kind exchanges and involuntary conversions - Basis and holding periods of assets |
| Federal Taxation of Individuals | 15-25% | - Pass-through entity income reporting - Adjustments, deductions, and credits - Loss limitations and tax computation - Filing status and exemptions - Gross income inclusions and exclusions |
| Federal Taxation of Entities | 28-38% | - C Corporations - S Corporations - Partnerships and LLCs - Tax-exempt organizations - Book-tax differences and distributions |
AICPA CPA Regulation Sample Questions:
A cash basis taxpayer should report gross income:
- A. Only for the year in which income is actually received whether in cash or in property.
- B. For the year in which income is either actually or constructively received in cash only.
- C. For the year in which income is either actually or constructively received, whether in cash or in
property. - D. Only for the year in which income is actually received in cash.
Correct Answer: C 🗳️
Explanation: Only visible for TestBraindump members. You can sign-up / login (it's free).
Cobb, an unmarried individual, had an adjusted gross income of $200,000 in 1990 before any IRA
deduction, taxable social security benefits, or passive activity losses. Cobb incurred a loss of $30,000 in
1 990 from rental real estate in which he actively participated. What amount of loss attributable to this
rental real estate can be used in 1990 as an offset against income from nonpassive sources?
- A. $0
- B. $12,500
- C. $30,000
- D. $25,000
Correct Answer: A 🗳️
Explanation: Only visible for TestBraindump members. You can sign-up / login (it's free).
Tom and Joan Moore, both CPAs, filed a joint 1994 federal income tax return showing $70,000 in taxable
income. During 1994, Tom's daughter Laura, age 16, resided with Tom. Laura had no income of her own
and was Tom's dependent.
Determine the amount of income or loss, if any that should be included on page one of the Moores' 1994
Form 1040.
The Moores had no capital loss carryovers from prior years. During 1994, the Moores had the following
stock transactions, which resulted in a net capital loss: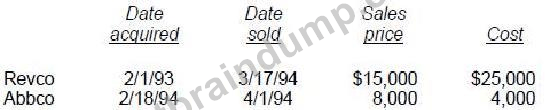
- A. $1,500
- B. $1,000
- C. $75,000
- D. $1,300
- E. $0
- F. $10,000
- G. $2,500
- H. $1,250
- I. $900
- J. $500
- K. $55,000
- L. $2,000
- M. $3,000
- N. $25,000
- O. $50,000
Correct Answer: M 🗳️
Explanation: Only visible for TestBraindump members. You can sign-up / login (it's free).
Hall, a divorced person and custodian of her 12-year old child, filed her 1990 federal income tax return as
head of a household. She submitted the following information to the CPA who prepared her 1990 return:
. The divorce agreement, executed in 1983, provides for Hall to receive $3,000 per month, of which $600
is designated as child support. After the child reaches 18, the monthly payments are to be reduced to
$ 2,400 and are to continue until remarriage or death. However, for the year 1990, Hall received a total of
only $5,000 from her former husband. Hall paid an attorney $2,000 in 1990 in a suit to collect the alimony
owed.
. In June 1990, Hall's mother gifted her 100 shares of a listed stock. The donor's basis for this stock, which
she bought in 1970, was $4,000, and market value on the date of the gift was $3,000. Hall sold this stock
in July 1990 for $3,500. The donor paid no gift tax.
. During 1990, Hall spent a total of $1,000 for state lottery tickets. Her lottery winnings in 1990 totaled
$ 200.
. Hall earned a salary of $25,000 in 1990. Hall was not covered by any type of retirement plan, but
contributed $2,000 to an IRA in 1990.
. In 1990, Hall sold an antique that she bought in 1980 to display in her home. Hall paid $800 for the
antique and sold it for $1,400, using the proceeds to pay a court-ordered judgment.
. Hall paid the following expenses in 1990 pertaining to the home that she owns: realty taxes, $3,400;
mortgage interest, $7,000; casualty insurance, $490; assessment by city for construction of a sewer
system, $910; interest of $1,000 on a personal, unsecured bank loan, the proceeds of which were used
for home improvements. Hall does not rent out any portion of the home.
What amount should be reported in Hall's 1990 return as alimony income?
- A. $5,000
- B. $0
- C. $28,800
- D. $36,000
Correct Answer: B 🗳️
Explanation: Only visible for TestBraindump members. You can sign-up / login (it's free).
Don Wolf became a general partner in Gata Associates on January 1, 1989, with a 5% interest in Gata's
profits, losses, and capital. Gata is a distributor of auto parts. Wolf does not materially participate in the
partnership business. For the year ended December 31, 1989, Gata had an operating loss of $100,000.
In addition, Gata earned interest of $20,000 on a temporary investment. Gata has kept the principal
temporarily invested while awaiting delivery of equipment that is presently on order. The principal will be
used to pay for this equipment. Wolf's passive loss for 1989 is:
- A. $5,000
- B. $0
- C. $4,000
- D. $6,000
Correct Answer: A 🗳️
Explanation: Only visible for TestBraindump members. You can sign-up / login (it's free).
Viewing page 1 out of 14 pages.
Viewing questions 1-5 out of 70 questions.
 Hubery

 Myra
 Moses

 Brian
 Calvin
 Barret

 Dennis
 Hazel
 Louis
 Les
 Les
 Bruce
 Kerwin
 Simona
 Martina